How much margin is safe? The honest answer isn't a number your broker enforces — it's a benchmark you enforce on yourself: keep your margin loan under roughly 30% of your portfolio's market value. That figure isn't a regulatory limit or a margin-call line. It's the discipline number I hold my own book below — and, not by accident, it's the top of what I call the Clear zone. Everything above it is survivable, but your options start narrowing the moment you cross it.
I run a leveraged book myself, so let me be precise about where 30% comes from, what it's 30% of (most people get the denominator wrong), and how to check where you actually sit this week — on your own numbers, not a hypothetical.
TL;DR
- The 30% rule = keep your margin loan under ~30% of your total portfolio value. It's a self-imposed discipline benchmark, not a broker rule.
- 30% of what? Your loan divided by the gross market value of your positions — not your net worth, not your cash-adjusted equity.
- Why below 30%? Your broker only forces action near 25–40% maintenance — by then you have no room. 30% keeps a cushion you control.
- What the rules actually require. The Federal Reserve's Regulation T currently lets you borrow up to 50% of a marginable purchase at the outset, and FINRA Rule 4210 sets a maintenance floor of 25% equity — which permits a loan of up to 75% of market value. Watch the unit: the maintenance floor is an equity ratio, not the loan ratio this page uses. And 30% is my ceiling, not theirs.
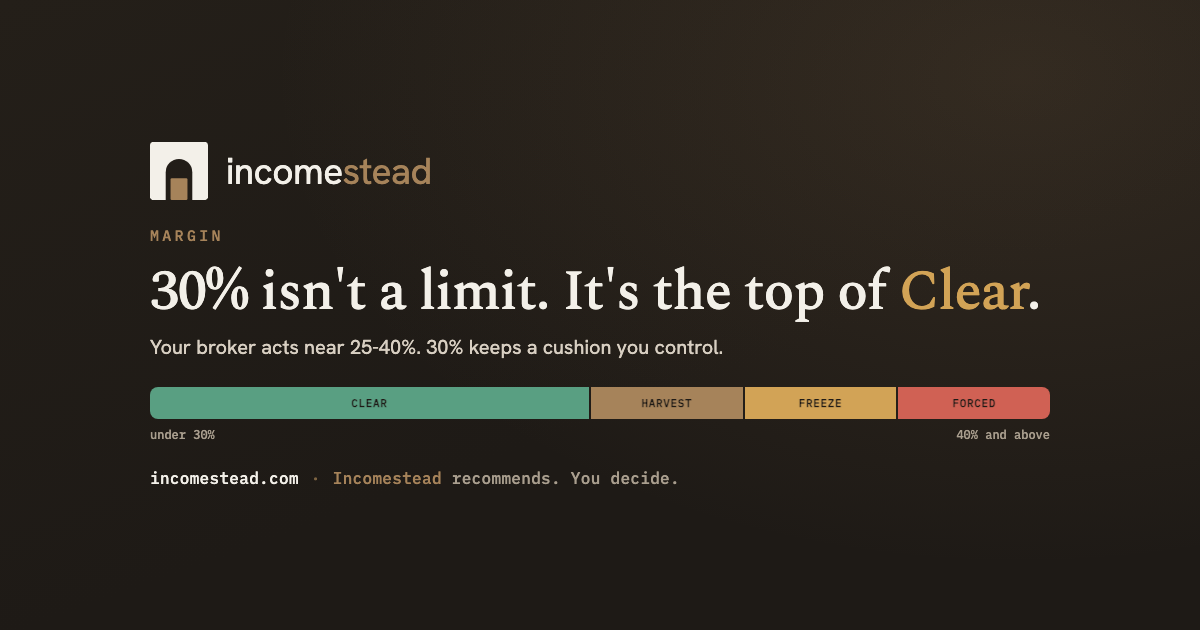
- 30% is the top of the Clear zone, not a target. Clear under 30 · Harvest 30 to under 35 · Freeze 35 to under 40 · Forced 40 and above.
- A market drop alone can push you up a zone without borrowing another dollar — which is why the ceiling is worth a number: at a 30% reading, the fall that reaches Forced is 25%.
Where does the 30% rule come from?
If you've read the private-banking playbook — borrow against assets instead of selling them, let the base compound, hand it down — you've met the strategy private banks market to wealthy clients. What rarely gets written down is the governor on it. The benchmark I hold to is a soft ceiling: keep the loan under about 30% of the assets backing it. Not because something breaks at 31%, but because a book that sits comfortably in the low-20s can absorb an ugly quarter without the borrower having to do anything at all. That same ceiling also sets the income your book has to earn to stand still. The same ceiling is the first condition on funding a retirement by borrowing — necessary, nowhere near sufficient.
Thirty percent is a behavioral benchmark, then — a line drawn well inside the danger, on purpose. It's the difference between borrowing like an institution and borrowing like someone who found out how much the broker would lend and treated that as the target.
The danger was never the tool. It was always the dose — and 30% is the dose the disciplined borrower refuses to exceed.
This is the same lens as whether margin is gambling: it isn't the borrowing that ruins people, it's the borrowing without a ceiling they enforce themselves.
30% of what? The number people get wrong
Here's where most people quietly miscalculate. Utilization is your margin loan divided by the gross market value of your positions — the full market value of what you hold, before subtracting the loan. Not your net worth. Not your house. Not your equity after the loan is netted out. Just: how big is the loan against the assets it's secured by?
Walk it through on real-shaped numbers. Say you hold $3,000,000 in positions and carry an $810,000 margin loan. Your utilization is $810,000 ÷ $3,000,000 = 27% — sitting in Clear, with a comfortable cushion.
Now here's the part that surprises people. You don't borrow another dollar, but the market falls 15%. Your positions are now worth $2,550,000; the loan is still $810,000. Utilization = $810,000 ÷ $2,550,000 ≈ 31.8% — you've crossed into Harvest without touching a single trade. A 30% drop would put the same loan at $810,000 ÷ $2,100,000 ≈ 38.6% — deep in Freeze, one bad month from Forced.
The market moves your utilization even when you don't. A book you set at 27% can be a 39% book after one ugly month — same dollars, smaller denominator.
That single mechanic is the entire argument for the cushion. Thirty percent isn't where you're safe — it's the highest number that still leaves you room to be wrong about the market before your broker gets a vote.
Why 30% and not the broker's margin-call line?
Because the broker's line is built to protect the broker, not you. Under the Federal Reserve's Regulation T, you can borrow up to 50% of the purchase price of marginable securities at the outset (FINRA, "Margin Regulation"). After that, FINRA Rule 4210 sets a maintenance minimum of 25% equity — the market value of your securities less what you owe — and most brokers impose higher "house" requirements, often 30–40%, which they can raise at any time without advance written notice.
Note the unit: the maintenance numbers are equity ratios, not the loan ratio this page uses, and the gap is not small. Twenty-five percent equity permits a loan of up to 75% of market value; a 40% house requirement, 60%. So my 30% ceiling is half the strictest of those lines and 40% of FINRA's floor. That distance is the whole product: it is what keeps the decision to sell mine. And the consequences are not gentle: as FINRA and the SEC both spell out, your broker can sell your securities without notifying you first, and you don't get to choose which ones (FINRA Rule 2264, "Margin Disclosure Statement"). A forced sale at the bottom, on assets you didn't pick to sell, in a week you didn't choose. That is the outcome the 30% rule exists to keep several moves away from you.
Keeping your loan under 30% means a market fall has to erase a lot of value before the broker's maintenance math ever becomes your problem. The gap between "what I'm allowed to borrow" and "what I choose to borrow" is the safety.
The four zones: Clear, Harvest, Freeze, Forced
A single utilization percentage is hard to feel. So instead of watching a scary continuous number tick up and down, read it as one of four states. This is the same gauge from the weekly margin management system — the full Clear / Harvest / Freeze / Forced framework lives there; here's the reference band:
| Zone | Utilization | What it means |
|---|---|---|
| Clear | < 30% | Clear. Room to absorb a drawdown without acting. Where the disciplined book lives. |
| Harvest | 30% to under 35% | Elevated. Direct new income to paying the loan down; stop adding leverage. |
| Freeze | 35% to under 40% | No new borrowing, no new risk. Actively reduce the loan. |
| Forced | ≥ 40% | Existential. Reduce now, on your terms — before the broker does it on theirs. |
House limits, not a regulatory standard — these bands are deliberately tighter than any broker or bank requirement.
Four zones is the easy part. The one that decides what you do this week is the zone your book is in — and that is one division you should not be doing in your head. The free Margin Zone Checker takes your loan and your market value and names it: Clear, Harvest, Freeze or Forced. It runs in your browser, and the figures you type never leave your device.
Read this way, "how much margin is safe?" has a calm answer: safe is Clear, and Clear ends at 30%. The zones turn a number you dread into a state you manage.
How far can the market fall before you're Forced?
Earlier I walked that same book down 15%, then 30%, to show that the market moves your reading even when you don't. Both were numbers I picked for you. Sitting on your own reading, the question you actually have runs the other way: how far can this book fall before it lands in Forced?
Hold the loan still for a moment. It does not fall when the market does — though it does accrue interest, which pushes the reading the same way and is its own arithmetic. With the loan held still, only the denominator moves, and the answer is one line:
Take the book from earlier — $3,000,000 of positions against an $810,000 loan, a reading of 27%. Forced opens at 40%. So 1 − (27 ÷ 40) = 32.5%.
But 32.5% is not your do-nothing room, and the difference matters more than the headline number. Run the same line against the nearer boundaries and that book leaves Clear on a 10% fall, and reaches Freeze — where the instruction is to actively reduce the loan — on 22.9%. The first thing you are asked to do arrives at an ordinary correction. Forced is only where the asking stops being optional.
So run it at both boundaries.
| Your reading | Fall to your next zone | Fall to Forced |
|---|---|---|
| 20% · Clear | 33.4% → Harvest | 50% |
| 25% · Clear | 16.7% → Harvest | 37.5% |
| 30% · Harvest opens | 14.3% → Freeze | 25% |
| 35% · Freeze opens | 12.5% → Forced | 12.5% |
| 38% · Freeze | 5% → Forced | 5% |
Read down the right-hand column and the shape is simple and unforgiving: every single point of utilization costs you 2.5 points of cushion — the same 2.5 points at 20% as at 38%. There is no stretch where a point is cheap. What changes is not the price, it is what you have left to spend: at 20% you are drawing on fifty points, at 38% on five.
Keep the loan under 30% and a 25% fall still leaves you short of Forced; at exactly 30%, that same fall puts you in it. Not a rounder-sounding rule and not a preference — just the arithmetic of a ceiling and a line that happen to be three-quarters of each other.
I am not forecasting a 25% fall, and nobody can tell you the odds of one. That is rather the point. You do not govern the size of the next drawdown; you govern how much of one your book can absorb before anyone else gets a vote. And note what none of these numbers is: Forced is a line I drew at 40%, not your broker's. Reaching it is not a margin call.
The Margin Zone Checker prints the Forced figure beside your zone — a fall of X% in portfolio value, loan unchanged, puts you there — so you don't have to re-run it every week.
Isn't watching my broker screen enough?
Your broker's screen shows you raw utilization — a live number that twitches with every tick. What it doesn't show you is a zone, and it definitely doesn't show you persistence. A book that spikes to 31% on a single volatile Tuesday and settles back to 26% by Friday didn't have a problem; it had a Tuesday. I have written up the two Fridays that taught me that difference on my own book — one where my gut was wrong, and one where it said nothing at all.
That's why the discipline isn't "act the instant the number crosses a line." It's the two-week persistence rule: a breach has to persist across two consecutive weekly readings before it drives an action. The rule applies with one deliberate exception — Forced, at 40% and above, acts on the first reading. One reading is noise. Two readings in a row is a trend — and a trend is what you govern. Reacting to every intraday flicker is how disciplined people exhaust themselves into bad decisions; waiting for persistence is how institutions stay calm.
One bad reading is a Tuesday. Two consecutive bad readings is a trend. You govern the trend, not the twitch.
How 30% ties to your Governance Score
The margin zone doesn't sit off by itself. It's one input into the Governance Score — a single number for how well you're governing your book overall, blending your margin zone, your allocation drift, and whether you actually run the check on a cadence. (The Incomestead engine treats these as one system rather than three dashboards.) The rule worth knowing here: a book sitting near Forced caps the whole Score, no matter how tidy everything else is. Existential risk gets first priority — margin before allocation, always — because a forced liquidation doesn't wait for you to fix your weights. If you want the arithmetic, here is how to work out your Governance Score by hand, component by component — or let the Governance Score tool on that page do the arithmetic for you.
Your margin governance and your Incomestead Stack — your target mix across strategy Layers — are the two things worth measuring every week. This post is about the first. But the reason margin comes first in the ordering is exactly the mechanic above: the market can move your zone against you overnight, and the broker's remedy is not on your schedule. A ceiling governs the loan and not the collateral, which is the sharpest thing said against this whole approach — why a crash can reprice the book faster than any zone can answer.
Find your zone in 60 seconds
Here's the one thing to do with your own account this week. No spreadsheet, no tool required:
- Pull two numbers from your brokerage: your margin loan balance and the gross market value of your positions.
- Divide the loan by the market value. That decimal × 100 is your utilization %.
- Find it on the band: under 30 Clear · 30 to under 35 Harvest · 35 to under 40 Freeze · 40 and above Forced.
- Now the governance move: imagine a 20% market drop — divide the same loan by 80% of your market value. That's the zone you're really carrying.
If the stress number lands in Freeze or Forced, you're not over-leveraged today — you're over-leveraged for the next bad month. That's the gap the 30% rule closes.
The sharper form: (1 − (your reading ÷ 40)) × 100 is your cushion to Forced, as a percentage — the fall this book could absorb before it gets there. If your reading is 40 or above the answer is zero or negative: you are already in Forced, and the cushion question no longer applies.
Do that every week and you're no longer guessing whether your leverage is safe — you're reading it. That weekly reading, held to a zone and a persistence rule, is the whole difference between borrowing like an operator and hoping like a gambler.
Run the 60-second check above on your real book this week — or skip the arithmetic. The Margin Zone Checker is live and free: put in your loan and market value and it reads your utilization back as a zone and shows your distance to Forced, so you never have to eyeball it again. It runs in your browser and your figures never leave it.
Frequently asked questions
How much margin is safe to use?
As a discipline benchmark, keep your margin loan under about 30% of the gross market value of your positions — the top of the Clear zone. This is a self-imposed ceiling drawn well inside the broker's margin-call math, not a regulatory limit. It leaves room for a market drawdown to move against you before you're forced to act.
What is the 30% rule for margin?
The 30% rule is my house rule: hold the margin loan below roughly 30% of the portfolio's market value. No regulator sets it. The reasoning is distance — borrow well inside what's allowed, so an ugly quarter doesn't trigger a forced sale.
Is 30% margin utilization the same as a margin call?
No. A margin call is triggered by your broker's maintenance requirement — FINRA's minimum is 25% equity, and house requirements are often 30–40% and can rise in volatile markets. The 30% rule is a self-imposed ceiling you set far below that danger zone, precisely so you never get near a call.
What happens if I go over 30%?
Nothing breaks at 31% — but you leave the Clear zone and your options narrow. In the Clear/Harvest/Freeze/Forced framework, 30% to under 35% (Harvest) means stop adding leverage and direct income toward the loan; 35% to under 40% (Freeze) means actively reduce; 40% and above (Forced) is existential. A breach that persists across two consecutive weekly readings is what should drive an action — not a single spike. The rule applies with one deliberate exception — Forced, at 40% and above, acts on the first reading.
Further than the point at which you should already have acted. FINRA's minimum is 25% equity, which permits a loan of up to 75% of market value, so a 30% book would have to fall 60% to reach it — or 50% to reach a stricter 40% house requirement, which the firm can raise without advance written notice. My own lines fire well before any of that: Freeze at 35% utilization says reduce the loan, and the Forced zone at 40% is reached by a fall of 1 − (your reading ÷ 40) — 25% from a 30% reading, 12.5% from 35%. The 30% rule exists so that you act at the first line and never meet the second.
How far can the market fall before I get a margin call?
Further than the point at which you should already have acted. FINRA's minimum is 25% equity, which permits a loan of up to 75% of market value, so a 30% book would have to fall 60% to reach it, or 50% to reach a stricter 40% house requirement, which the firm can raise without advance written notice. Incomestead's own lines fire well before any of that: Freeze at 35% utilization says reduce the loan, and the Forced zone at 40% is reached by a fall of 1 minus (your reading divided by 40) — 25% from a 30% reading, 12.5% from 35%. The 30% rule exists so that you act at the first line and never meet the second.
Can my broker sell my stocks if I'm on margin?
Yes. If your equity falls below the maintenance requirement, your broker can sell securities in your account to cover the shortfall — and, as FINRA and the SEC note, it can do so without contacting you first, and you don't get to choose which positions are sold. Keeping your loan under 30% is how you keep that decision in your own hands.
This is education, not personalized financial advice. I write as a practitioner who runs a leveraged book, not as a licensed adviser. Margin amplifies losses as well as gains; a broker can liquidate your positions without notice, and portfolio-margin requirements can rise in volatile markets. Figures cited are from FINRA and SEC investor materials as of the review date — verify current requirements with your own broker before acting. Nothing here recommends how much you should borrow.
Incomestead recommends. You decide.